Policy Mechanics – Cash Flow
Universal Life Insurance – COI – Cost of Insurance
Universal Life – Cost of Insurance
- Lawsuits
- select and ultimate
- One very ominous trend is a movement toward select and ultimate mortality charges on Universal Life, and this is one that hopefully will stop.
- We hope that the companies will not follow the same suicidal tendencies with Universal Life that they’ve followed with annual renewable term down the select and ultimate path.
- Universal Life has been promoted by a number of people as an alternative to the self-destructive practices that the industry has followed on annual renewable term, so hopefully we will not make the same mistake again.
1983 – SOA – Universal Life (rsa83v9n32), Society of Actuaries – 22p
- Another possibility that may have merit is to charge select and ultimate premiums for the pure insurance component of a universal life plan.
- However, we agree with Mr. Smith and dozens of other actuaries with whom we have discussed S/U ART that those companies selling products (be they term or “whole life”) with select premiums may be asking for trouble.
- Time will tell whether trouble will respond, but we expect it will.
— Authors’ Review of Discussion – Jeffery Dukes and Andrew M. Mac Donald
1980 – SOA – Pricing a Select and Ultimate Annual Renewable Term Product, Society of Actuaries – 38p
Zero Return, Still Have COI – So the Account Value Can Go Down
Zero Return, Still Have COI – So the Account Value Can Go Down
- 2024 0308 – Cody Askins – 3 Ways To Sell Indexed Universal Life Policies As An Insurance Agent! (NEED TO KNOW) – [VIDEO-YouTube-11:25]
- 6 – Performance
- “You can get a Zero. Everybody’s selling that there is Zero Risk. Everything has risk.”
- “Can the floor of an IUL product be Zero? Let’s just say S&P 500 gives a negative 18% return. Can the policy be credited with a Zero and actually receive a Zero and not the negative 18%? Yes, however, you still have to pay for Cost of Insurance. What does that mean? That if a policy gets a Zero on a down year, which is good, there’s still some security there. That’s great. They are still having to pay the Cost of Insurance which means that the account can actually go backwards. Because you actually have to pay for the Cost of Insurance. Which is important.”
- 8 – IUL’s have their place, Some people are selling it as the end all be all – The only option on the planet.
- 6 – Performance
- I tell clients that the cash value is guaranteed not to go down when the market goes down because the cash value has a 0% annual floor.
— Declaration of Sean L. Covi, Agent – Doc 258 – 2010 0710 – 11p
2000s – LC – Walker v LSW (Life Insurance Company of the Southwest) — [BonkNote]
No Premium Due
No Premium Due
- Commissioner Willis (DC) said the trouble with disclosing that the premium might at some point “resume” is that the premium never stopped.
- It is misleading to make a consumer think the premium is not being paid.
- [Bonk: Vanishing Premium, Policy Mechanics, Cash Flow, Work)
1994-3, NAIC Proceedings
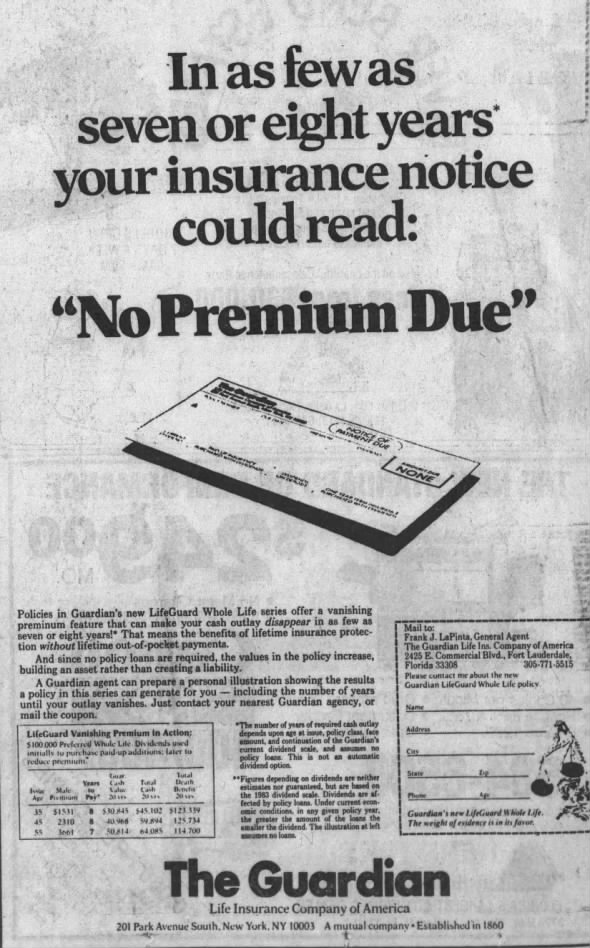
1983 0206 – Fort Lauderdale News – Guardian – Vanishing Premium – LifeGuard Whole Life – p78 – Newspapers.com
IRR – Internal Rate of Return
IRR – Internal Rate of Return
- 2021 – AP – A Study of Life Internal Rate of Return, by Roenganan, Sorrawee & Misiran, Masnita & Phewchean, Nattakorn. (2021). A Study of Life Internal Rate of Return. WSEAS TRANSACTIONS ON MATHEMATICS. 20. 122-133 – [link]
Pricing Assumptions
Pricing Assumptions
- Actually, all of us know it is one thing to build into your pricing assumptions a certain rate of return, but it is quite another thing to find out what rate of return you are actually experiencing.
— Owen A. Reed
1981 – SOA – Effective Use of Capital, rsa81v7n312, Society of Actuaries – 24p
- Premium Considerations
- The non-guaranteed premium concept can be utilized for all forms of nonparticipating insurance, including both term and permanent policies.
- In setting insurance premiums, the actuary can use pricing assumptions that are as realistic as possible.
- The actuary is not locked into “50 years” of insufficient premiums if his or her estimates of future assumptions prove to be too optimistic.
— Richard A. Swift – [Bonk: Aetna-?]
1980 – SOA – Nonparticipating Life Products with Nonguaranteed Premiums (rsa80v6n22), Society of Actuaries – 18p
Cost
Net Cost
Net Cost
- A. “Net cost formulas at present in use for participating insurance should be superseded by a sound net cost formula which would include the investment value of the premium dollar and ignore the averaging of dividends.”
- In view of the above and similar criticisms, are the traditional average net cost and average net payment illustrations still satisfactory?
- How far should companies go in assuming a rate of interest for projected accumulations?
1962 – SOA – Digest of Discussion of Subjects of Special Interest Individual Life Insurance, Society of Actuaries – 4p
- The Effects of the Proposed Changes In The Standard Valuation and Nonforfeiture Value Laws on Reserves, Surrender Values, Net Costs and Yields
1981-1, NAIC Proceedings – Task Force on Life Insurance Disclosure System – LIDS – NAIC — [BonkNote]
Volatility
Volatility
- Volatility – Walker v LSW
- Volatility Buffer
- I think you really have to make sure that people understand volatility, whether you solve for a policy blowing up or values being halved.
- I think you have to catch people’s attention, and that is all to the good.
— George Coleman, Prudential, ACLI, TRG-Technical Resource Group for the NAIC (Industry Advisory Group – Illustrations)
1994 – SOA – Problems and Solutions for Product Illustrations, Society of Actuaries – 28p
- 2019 0312 – 2019-1, NAIC Proc. – IUL Illustration (A) Subgroup, Conference Call
- Mr. Tsang said the illustration should be used to manage policyholder expectations and should show the volatility of returns, so the policyholder has a realistic picture of the risks.
- Brian Lessing (AXA) said it is difficult to illustrate the volatility, which is why in-force illustrations are so important.
Front-end Loads
Front-end Loads
- (p10) – Claude Y. Pauquin: Another thought that I had on the front-end load is that “what is good for the goose is good for the gander.
- If the SEC successfully attacks the principle of front-end load in mutual funds, it might also destroy the marketing approach of the life insurance business, especially if federal controls of the life insurance business are forthcoming, since the federal insurance regulators might be expected to adopt a philosophy not too different from that of the securities regulators.
1967 – SOA – New-Company Problems, Society of Actuaries – 38p
BGA – Benefit Generating Account
BGA – Benefit Generating Account
- This creature called universal life has evolved from a combination of term insurance and a flexible premium annuity to a range of differing products with various design features.
- Common to any of these variations is the fact that future cash values cannot be determined completely at issue.
- Cash values (and other benefits) are produced by a formula that is specified in advance. Some of the various elements used in the formula, however, can be adjusted after issue by the insurer.
- 6. THE CONCEPT OF THE BENEFIT GENERATING ACCOUNT
- We have mentioned several times that the function of the account value is to determine future benefits.
1983 – SOA – Universal Life Valuation and Nonforfeiture: A Generalized Model, Shane A. Chalke and Michael F. Davlin, Society of Actuaries – 72p