Premium
Guaranteed Maturity Premium Nonforfeiture Test
Guaranteed Maturity Premium Nonforfeiture Test
- p412 - Enclosure 5 - Guaranteed Maturity Premium Nonforfeiture Test
- The guaranteed maturity premium (GMP) test is a proposed method fur judging whether or not a universal life product provides guaranteed cash surrender values in excess of prescribed minimums.
- The GMP test is concerned primarily with the pattern of policy loads and surrender charges. When used in conjunction with a prescribed smoothness of cash value criteria, the GMP test is effective in disqualifying policies with odd patterns of loads or those with high loads over a sustained number of years.
- The guaranteed maturify premium is calculated as prescribed in the NAIC Universal Life Model Regulation. It is calculated without regard to any minimum premiums required by the company.
1988-2, NAIC Proceedings - Life and Health Actuarial (EX5) Task Force
Universal Life Insurance – COI – Cost of Insurance
Universal Life – Cost of Insurance
- Lawsuits
- select and ultimate
- One very ominous trend is a movement toward select and ultimate mortality charges on Universal Life, and this is one that hopefully will stop.
- We hope that the companies will not follow the same suicidal tendencies with Universal Life that they’ve followed with annual renewable term down the select and ultimate path.
- Universal Life has been promoted by a number of people as an alternative to the self-destructive practices that the industry has followed on annual renewable term, so hopefully we will not make the same mistake again.
1983 – SOA – Universal Life (rsa83v9n32), Society of Actuaries – 22p
- Another possibility that may have merit is to charge select and ultimate premiums for the pure insurance component of a universal life plan.
- However, we agree with Mr. Smith and dozens of other actuaries with whom we have discussed S/U ART that those companies selling products (be they term or “whole life”) with select premiums may be asking for trouble.
- Time will tell whether trouble will respond, but we expect it will.
— Authors’ Review of Discussion – Jeffery Dukes and Andrew M. Mac Donald
1980 – SOA – Pricing a Select and Ultimate Annual Renewable Term Product, Society of Actuaries – 38p
Required Minimum Premium
Required Minimum Premium
- * Paying more than the required minimum premium can help build cash value
2021 – Prudential – Cash Value: Life Insurance in Retirement Planning – 2p
Unisex
Unisex
- 1984 – SOA – Unisex – An Update, rsa84v10n215 – Society of Actuaries – 14p
- Moderator: DAPHNE D, BARTLETT. Panelists: THOMAS P. BLEAKNEY, BARBARA J. LAUTZENHEISER, ANTHONY T. SPANO. Recorder: MICHAEL F. DAVLIN
Maximum Premium
Maximum Premium
- (9) A brief description of the premium outlay or contract premium, if applicable, required by the policy.
- For a policy which does not require a specific premium payment, a statement as to what premium outlay must be paid to guarantee coverage for the term of the contract, subject to maximum premiums allowable to qualify as life insurance under the applicable provisions of the Internal Revenue Code;
ATTACHMENT THREE-A – ILLUSTRATIONS USED IN CONNECTION WITH THE SALE OF LIFE INSURANCE MODEL REGULATION – Draft: 12/3/94
1994-4, NAIC Proceedings
- p33 – Common issue 8: maximum premium
- ⇒ Kevin Morrissey, a Vice President of Sun Life, had deposed in the course of the Indemnity Litigation that “the year 2030 is the median point at which Universal Plus policyholders are likely be required to pay an amount in excess of the ‘Maximum Premium’ set out in their policy specifications pages.”
2018 0905 – LC – Fehr v. Sun Life – Decision – Ontario – Court of Appeal — [BonkNote] — 73p
Graded Premiums
Graded Premiums
- 1959 – SOA – Discussion of Subjects of Special Interest – Graded Premiums, Society of Actuaries VOL. 11 NO. 29AB – 6p
Hyperfunding
Hyperfunding
- 2014 0928 – Letter – Sheryl J. Moore to NAIC (LATF) – Moore Market Intelligence – RE: Actuarial Guideline on Illustrations for Indexed Life Insurance Policies – [link]
- 2017 0522 – Veralytic – Criticism of Hybrid Life Insurance Products – [Barry Flagg] – [VIDEO-YouTube-46:56]
- SEC 151A, Harkin Amendment
- Red Flags
- 35 – HyperFunding
- 2024 0725 – BetterWealth – Exposing Curtis Ray: Attorney Reveals The Dangers of MPI – [Roccy DeFrancesco] — [BonkNote] — [VIDEO-YouTube-28:22]
No Premium Due
No Premium Due
- Commissioner Willis (DC) said the trouble with disclosing that the premium might at some point “resume” is that the premium never stopped.
- It is misleading to make a consumer think the premium is not being paid.
- [Bonk: Vanishing Premium, Policy Mechanics, Cash Flow, Work)
1994-3, NAIC Proceedings
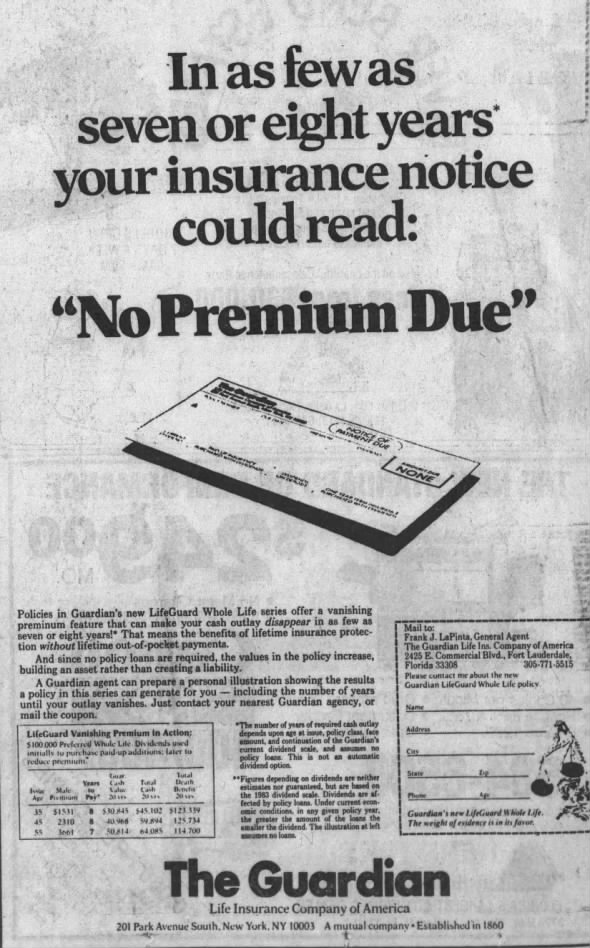
1983 0206 – Fort Lauderdale News – Guardian – Vanishing Premium – LifeGuard Whole Life – p78 – Newspapers.com
Fractional Premiums
Fractional Premiums
- Robert G. Ward opened the discussion by describing the basis of fractional premiums introduced by the Provident Mutual late in 1957, at which time a system of quantity discount was announced under which the premium for yearly premium life insurance policies was $2 less per $1,000 on the portion of a policy in excess of $4,000 insurance.
- The factors which increase the cost of fractional premiums over yearly premiums are (1) loss of interest on premiums paid other than yearly, (2) loss of uncollected fractional premiums in the year of death and (3) the cost of additional premium collections.
- The first two factors are related to the amount of the premium while the third is a “per policy” expense independent of the premium or amount of insurance.
1960 – SOA – Discussion of Subjects of Special Interest: Fractional Premiums, Society of Actuaries – 3p
Net Premium
Net Premium
- The method of computation of “net premium” is the great insurance secret.
- We doubt if any legislator or any judge ever solved the problem or guessed the secret. (p66)
1917 – Book – A License to Steal: Life Insurance, the Swindle of Swindles : how Our Laws Rob Our Own People of Billions, by Philander Banister Armstrong – [305p-GooglePlay]
- (p323) – 14.4 Universal Life Insurance Model Regulation
- Flexible premium products introduce special valuation problems using traditional methods in that some assumption as to future premiums is required.
- The typical “present value of future benefits less the present value of future net premiums” formula is challenging to apply to flexible premium universal life policies, since neither “future premiums” nor “future benefits” are known for any particular policy.
2018 – Book – Statutory Valuation of Individual Life and Annuity Contracts | 5th Edition — by Donna Claire, Lombardi and Summers
- … when we come to value policies afterwards is a very different question indeed; and I, for one, cannot get over the dictum laid down by Professor De Morgan, that we have to deal with facts.
- A man is aged x.
- Well, you must charge yourself with the present value of the assurance upon that man, an credit for a portion of his premiums, that portion being what is conventionally known as the net premium.
- Now what is net premium?
- There has been a great deal of paltering with that.
- Any person that will look carefully into the valuations will find that what some actuaries call a net premium is a net premium at variance with the data which they profess to be valuing.
- That is not net premium, and it has done much detriment in many companies.
- But that is a different question altogether.
1875 10 – Actuarial Paper – The Measure of Expenses in Life Assurance Companies, by James R. Macfadyen, Journal of the Institute of Actuaries and Assurance Magazine, Vol. 19, No. 3, pp. 153-174 – (23p – JSTOR)